What Travel Insurance Actually Covers
“What does travel insurance actually cover?” It’s one of the questions we hear most often at Every Moment Travels, usually from a client mid-way through processing their travel documents, right after the excitement of a confirmed flight meets the reality of “what if something goes wrong.”
And things do go wrong — a sudden illness, a canceled flight, a missing suitcase, a family emergency back home. None of these are rare; they’re just the ordinary risks of travel. Travel insurance is the safety net built specifically for them.
It’s easy to see insurance as something you buy “just in case” and hope never to use. But experienced travelers tend to see it differently: less about fear, more about not letting one bad afternoon turn into a financial setback. This guide breaks down exactly what a typical policy covers, what it usually excludes, and how to choose the right plan for your trip.
What Is Travel Insurance?
Travel insurance is a short-term policy built to protect you from financial losses connected to travel — medical emergencies abroad, trip cancellation or interruption, lost or delayed baggage, emergency evacuation, and travel delays. Instead of paying these costs entirely out of pocket, your policy covers some or all of the expense, which can mean the difference between an inconvenience and a genuine financial setback.
The Core Types of Coverage
1. Medical Coverage
This is the backbone of most policies, especially for international travel. It typically covers doctor visits, hospital stays, emergency treatment, prescription medication, limited emergency dental care, and ambulance services.
Healthcare costs vary hugely by country, and travelers are consistently surprised by how expensive care is in places like the US, Canada, or parts of Europe — a short hospital visit without coverage can run into thousands of dollars fast. It’s also worth remembering that your regular health insurance often doesn’t follow you abroad, or only offers limited reimbursement, which is exactly the gap travel medical coverage is built to fill.
Coverage limits usually fall into a few tiers — $50,000, $100,000, or $250,000 and above. For international trips, we generally recommend leaning toward the higher end, since the difference in premium is usually smaller than the difference in protection.
2. Trip Cancellation Coverage
Flights, hotels, tours — a lot of travel spending is non-refundable. Trip cancellation coverage protects that investment if you have to cancel before departure for a covered reason: sudden illness or injury, the death of a close family member, a natural disaster, severe weather, jury duty, or a travel supplier going bankrupt. If your reason qualifies, the insurer reimburses your prepaid, non-refundable expenses — airline tickets, hotel bookings, tour packages, cruise costs, and event fees.
3. Trip Interruption Coverage
This kicks in once your trip has already started. If a family emergency, sudden illness, or unrest at your destination forces you to cut the trip short, this coverage helps pay for unused portions of the trip, additional transportation home, and emergency accommodation changes — so you’re not absorbing that loss on top of an already stressful situation.
4. Baggage and Personal Belongings Coverage
Lost luggage remains one of the most common — and most frustrating — travel problems. This coverage protects belongings that are lost, stolen, or damaged, typically up to a total limit with smaller sub-limits for electronics. If your bag is delayed rather than lost, many plans also reimburse essentials like clothing, toiletries, and chargers so you can keep your trip moving while you wait.
5. Emergency Evacuation and Repatriation Coverage
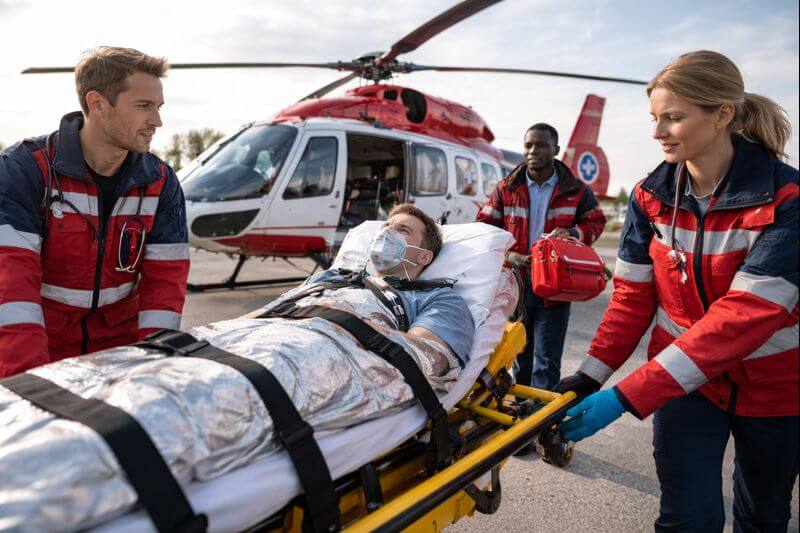
This is one of the most expensive things that can happen on a trip, and one of the most commonly overlooked. If you’re seriously ill or injured and local facilities aren’t adequate, this coverage pays for transport to a better hospital, another city, or your home country — evacuations often involve air ambulances, which can run into the tens of thousands of dollars without coverage. In the rare case of death abroad, this category also typically covers the legal and transportation costs of repatriating remains.
6. Travel Delay and Missed Connection Coverage
Delays happen more than any of us would like. This reimburses additional expenses caused by flight delays, missed connections, or an overnight stay forced by an airline issue — commonly hotel accommodation, meals, and local transportation.
7. 24/7 Travel Assistance
Many policies include round-the-clock assistance that’s easy to overlook until you actually need it: help finding a nearby hospital or doctor, replacing a lost passport, arranging emergency transport, navigating an unfamiliar healthcare system, or getting help in a language you don’t speak. When you’re stressed in an unfamiliar country, this kind of support matters more than it sounds like it would.
What Travel Insurance Usually Does Not Cover
Knowing the exclusions matters just as much as knowing the coverage.
Pre-existing medical conditions are commonly excluded unless you specifically purchase a waiver at the time of buying your policy.
High-risk or extreme activities — skydiving, deep scuba diving, mountaineering — often require add-on coverage rather than being included by default.
Illegal or reckless behavior, including claims connected to substance use, is typically excluded outright.
Travel against official government advisories can void coverage for that destination, even if the rest of your policy is valid.
Normal wear and tear on belongings — as opposed to loss, theft, or accidental damage — is generally not covered.
Optional Add-Ons Worth Considering
Cancel For Any Reason (CFAR) extends cancellation coverage beyond the standard list of covered reasons, offering more flexibility (and partial reimbursement) at a higher premium.
Rental car coverage protects against damage or theft of a rental vehicle during your trip.
Adventure sports coverage is worth adding if your itinerary includes anything physically demanding or higher-risk than standard sightseeing.
How Coverage Plays Out in Practice
A traveler falls ill overseas and needs hospitalization — medical coverage handles treatment and medication. A family emergency forces a last-minute cancellation — trip cancellation coverage reimburses the prepaid, non-refundable costs. A suitcase goes missing in transit — baggage coverage reimburses clothing and essentials while you sort it out. These aren’t edge cases; they’re the ordinary situations this kind of coverage exists for.
How to Choose the Right Plan
- Consider your destination and its typical healthcare costs
- Check the medical coverage limit against what you’d actually want if something serious happened
- Read the exclusions carefully, not just the headline coverage
- Compare a few providers rather than defaulting to the first one you find
- Buy soon after booking — this is what activates cancellation benefits from the earliest point
Travel Insurance vs. Credit Card Coverage
Many travelers assume their credit card already covers them. It rarely does to the same extent:
| Feature | Travel Insurance | Credit Card |
|---|---|---|
| Medical Coverage | Yes | Limited |
| Trip Cancellation | Yes | Limited |
| Baggage Coverage | Yes | Sometimes |
| Emergency Evacuation | Yes | Rarely |
Credit card benefits are worth using as a supplement, but they’re generally not a substitute for a dedicated policy — particularly on the medical evacuation side, where card coverage is thinnest.
Is Travel Insurance Worth It?
Travel insurance tends to feel optional right up until the moment you need it. Between medical emergencies, cancellations, lost luggage, and evacuation, it protects your money and your health at the same time — and for most international trips, the cost is a small fraction of what a single uninsured incident could cost you.
Whether you’re traveling for vacation, business, study, or adventure, understanding exactly what your policy covers — and what it doesn’t — means you can focus on the trip itself instead of what might go wrong along the way.