Introduction
“Travel insurance” and “international health insurance” are often used interchangeably, but picking the wrong one can cost you tens of thousands of dollars. As of 2026, the travel landscape has shifted — medical costs in popular destinations like the US and Japan have kept climbing, and living a “border-less” life, whether as a digital nomad or a long-term expat, is more common than ever.
Whether you’re planning a two-week safari in Kenya, a few months working remotely from Bali, or a permanent move to the south of France, one question matters more than your packing list: how will you be covered if you get sick? This guide breaks down the difference between these two products so you’re not caught off guard.
The Misunderstanding That Costs People Money
Imagine this: you’re hiking in the Swiss Alps, you trip and shatter your ankle. A helicopter rescue runs around $15,000, and the surgery plus a three-day hospital stay adds another $45,000.
If you have travel insurance, you’re likely covered — provided the hike isn’t classified as an “extreme sport” exclusion. But if you develop a chronic condition while living abroad and expect your travel policy to pay for ongoing monthly treatment, you’re in for a shock. Travel insurance is built to stabilize you and send you home. It’s a safety net, not a healthcare plan.
According to IMARC Group’s 2025 market research, medical expense coverage is the largest single category in the travel insurance market, accounting for 41% of the market. Travelers are increasingly realizing that their domestic health plans — Medicare in the US, the NHS in the UK — generally stop working the moment they cross a border.
Choosing the Right Coverage, Step by Step
Step 1: Define your duration
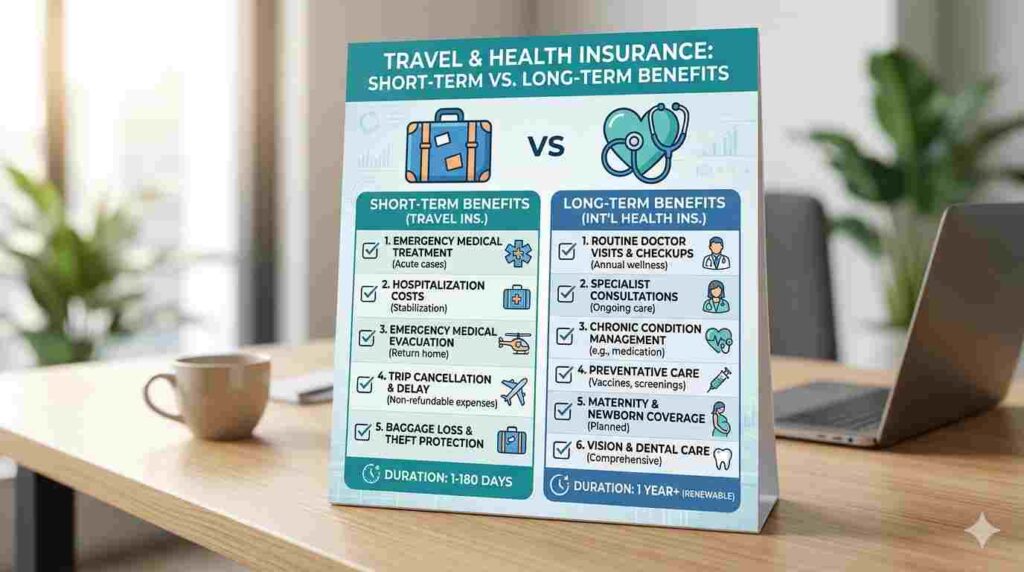
- Under 3 months: standard travel insurance is usually enough. It covers the short-term spike in risk that comes with a trip.
- 6 months to a year or more: you’re likely functioning as an expat or long-term traveler, and you need international health insurance (sometimes called IPMI).
Step 2: Evaluate your “home” coverage
Are you keeping your domestic insurance active? If so, travel insurance can act as a bridge. If you’re canceling your home plan, you need an international health plan that covers preventative, chronic, and routine care — not just emergencies.
Step 3: Check mandatory requirements
In 2026, several regions — the Schengen Area and parts of Southeast Asia among them — require proof of insurance. Make sure your policy meets the minimum medical limit for your destination: typically €30,000 for Europe, or around $50,000 for other regions.
Step 4: Audit your activities
If you’re diving, skiing, or riding motorbikes, a standard health plan may cover the medical side, but usually only travel insurance includes search-and-rescue or repatriation coverage.
Travel Insurance vs. International Health Insurance, at a Glance
| Feature | Travel Insurance | International Health Insurance |
|---|---|---|
| Best for | Holidays, business trips, vacations | Expats, digital nomads, overseas workers |
| Primary goal | Emergency stabilization and trip protection | Long-term health maintenance and wellness |
| Medical coverage | New, unexpected emergencies only | Routine care, chronic conditions, emergencies |
| Trip protection | Flight delays, lost luggage, theft | Usually excluded (medical only) |
| Duration | One day to roughly 180 days | One year, renewable |
| Evacuation | Included (return to home country) | Included (transport to nearest suitable facility) |
| Cost basis | Age, trip cost, and duration | Age, area of coverage, and medical history |
What Each One Actually Covers
Travel insurance is a multi-risk package built to protect the money you’ve put into a trip. If your airline goes under or your bag is stolen in Barcelona, this is what steps in. It’s best thought of as disruption insurance with an emergency medical add-on — it assumes you have a home to recover in once the emergency passes. If you want the full picture, our guide to what travel insurance covers goes deeper.
International health insurance (also called expat insurance) is closer to a lifestyle product. It works like the health plan you’d have at home, but globally, and typically includes inpatient and outpatient care, maternity and newborn care, prescription medication for chronic conditions like high blood pressure or asthma, and cancer treatment and physical therapy.
2026 Checklist Before You Buy
- [ ] Emergency medical limit — minimum $100,000; $250,000 recommended if you’re headed to the US or Japan.
- [ ] Medical evacuation — minimum $250,000. A private medevac flight from Asia to the US can run well over $100,000.
- [ ] Pre-existing condition waiver — do you need coverage for a condition you already have?
- [ ] Repatriation of remains — covers returning your body home in a worst-case scenario.
- [ ] Crisis response — coverage for natural disasters or political unrest.
- [ ] Deductible/excess — is the out-of-pocket cost per incident, or per policy?
The Numbers Behind 2026 Travel Risk
Emergency costs abroad vary widely by country and situation, but as a rough guide: a ground ambulance in the US can run over $1,000, a hospital room in Japan can cost several hundred dollars a night, and a long-haul international medical evacuation can run into six figures — sometimes well over $100,000. Insurance industry research (IMARC Group, 2025) also shows travelers aged 60 and over now make up roughly 31% of the travel insurance market, which is driving demand for higher medical coverage limits generally.
Tips for Saving Money
- Check your credit card first. Some premium cards offer trip cancellation coverage, but very few offer robust medical coverage. Use the card for the “trip” side and buy a medical-only travel policy separately — it’s often cheaper than a bundled plan.
- Consider an annual multi-trip policy. If you travel more than a few times a year, this is almost always cheaper than buying individual plans each time.
- Look for “visa-compliant” plans if that’s all you need. These strip out baggage and theft coverage to lower the price when your only requirement is meeting a visa’s medical insurance minimum. Our guide to the best travel insurance for Europe covers this in more detail.
Common Mistakes to Avoid
- Assuming “global” includes the US. Most international health plans offer two tiers — “worldwide” and “worldwide excluding USA” — and the latter is significantly cheaper. Check which one you’re buying.
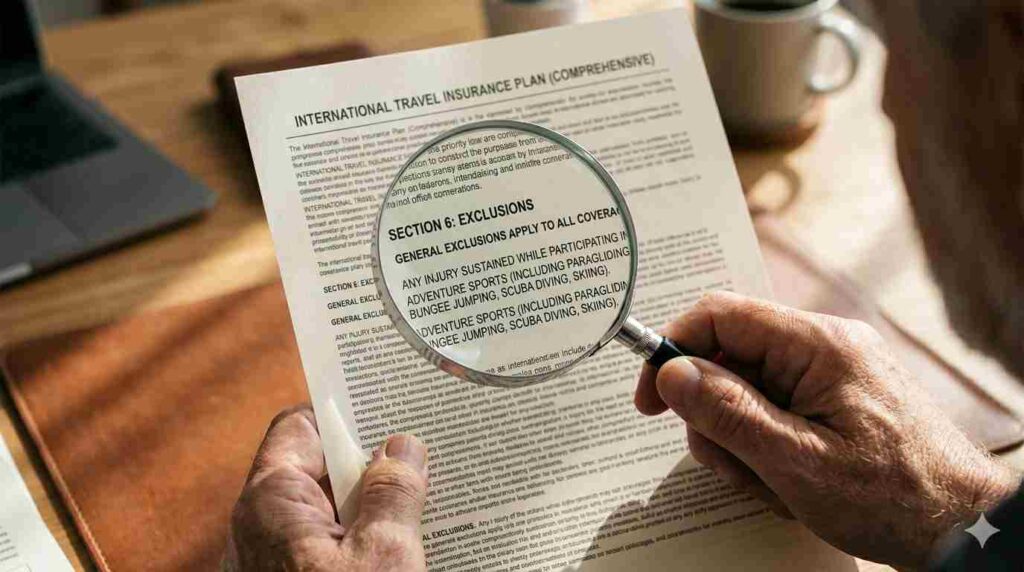
- Ignoring the adventure sports clause. Standard travel insurance often excludes hiking above 2,500 meters, scuba diving below 10 meters, or riding a scooter without a local license.
- Not declaring pre-existing conditions. If you have diabetes and don’t disclose it, any claim connected to your blood sugar — even an accident caused by a dizzy spell — is likely to be denied.
Frequently Asked Questions
Does travel insurance cover COVID-19 in 2026? Yes. Most reputable providers now treat COVID-19 like any other unexpected illness, covering hospitalization and medically mandated quarantine costs.
Can I buy travel insurance after I’ve already left home? Most companies require you to purchase before departure. A few digital-nomad-focused insurers, like SafetyWing or World Nomads, let you start a policy while already abroad, typically with a 48–72 hour waiting period.
Does health insurance cover a lost laptop? No. International health insurance is strictly medical. You’d need a separate personal-effects policy, or a travel insurance plan that covers gear and tech.
Conclusion
The choice between travel insurance and international health insurance comes down to intent. If you’re visiting, travel insurance protects your wallet from the chaos of travel. If you’re living somewhere — even temporarily — international health insurance is what keeps you from draining your savings on routine and ongoing care.
In 2026, traveling uninsured isn’t just a bad-luck scenario. With medical costs rising steadily, it’s a financial risk worth checking before you
The choice between travel insurance and international health insurance comes down to intent.
If you are a visitor, Travel Insurance is your best friend—it protects your wallet from the chaos of travel. If you are a resident (even a temporary one), International Health Insurance is your lifeline—it ensures you have access to quality care without draining your life savings. In 2026, the risk of traveling uninsured is no longer just a “bad luck” scenario; with medical inflation rising, it’s a financial gamble you cannot afford to lose. Check your policy today—before the wheels go up.